The family’s safety

Life insurance: a safety net beneath the family

Term life insurance alongside a loan, for family protection or as a company benefit. The question is not just whether you need it – but also how big a net you need, and at what price. If it turns out that taking out cover now isn't the right move, I'll say so too. I help you answer that impartially.

Plan Tower

Mini game · 30 seconds

🎮 Plan Tower – every floor is a plan, and the protection level holds it!

Why with me?

Sized to a real amount

Loan, income replacement, education – we calculate the cover that genuinely protects.

For companies: as a group

Group life and accident insurance is an attractive, tax-efficient benefit – on request I run that competition too.

At the renewal date, if you let me know, I review it again

Life changes – the cover must follow.

How does it work?

A conversation

20 minutes by phone or video: your situation, your goals, your budget. Free of charge, with no obligation.

Competition

I collect offers from the relevant insurers and hand them over in a single, easy-to-read table – strengths and weaknesses included.

Decision & beyond

You decide, I handle the paperwork. If you have a question later or your situation changes, let me know – and when a claim comes, I help you get started.

Insights – 84 plain-language articles

The former quick guides have grown into a full knowledge base: basics, sizing the cover, types and riders, the health declaration, beneficiaries and inheritance, life situations, claims, checklists – searchable with the magnifier button in the header.

Frequently asked questions

How big should the sum assured be?

Loans, the family’s annual expenses and the years of income to replace add up together – plus education, if that is a goal. We size it from your numbers, not from a rule of thumb.

Term or savings-type life insurance?

Pure term cover has no savings component, so the same premium typically buys a significantly higher sum insured: high sum, low premium. Savings goals are often more efficient in a separate vehicle – it pays to separate the two deliberately.

Is a health declaration or medical exam needed?

Individual policies typically require a declaration, and higher sums may need an exam. In a corporate group frame, however, there is typically no individual underwriting – see csoportos.biz.

Do I have to accept the bank’s life policy with my loan?

No: you can typically choose the cover freely; the bank’s requirement is the beneficiary/assignment clause. Competition often yields better terms.

What happens at renewal?

Life changes: loans shrink, children arrive, income grows. At the renewal date, if you let me know, I review the sum and the premium – the cover should follow your life, not the other way round.

All questions – the FAQ page (36) →

Useful documents

Product summary – on one pagePDF
Download ↓

More aids – checklists and guides – on the Resources page.

Panni, Boti and little Bogyó – the net is invisible, yet it holds the whole family.

Request a quote – the first step is a 20-minute call.

As an independent broker I make insurers compete for you – not the other way round. My advice costs you nothing.

Book an appointment

The broker

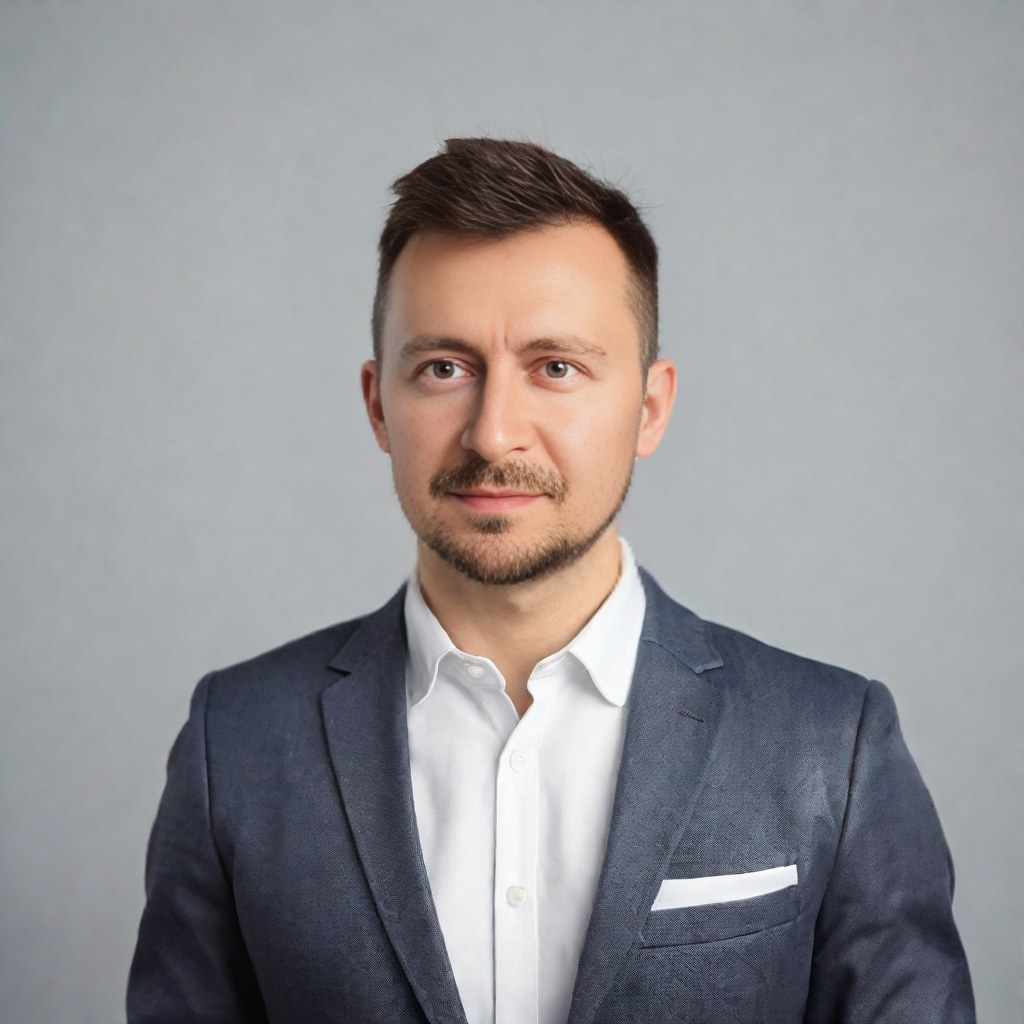
Portrait of Emánuel Dávid Tukacs, independent insurance broker

elet.biz is the information and quote-request page of Emánuel Dávid Tukacs, independent insurance broker. As a broker I act on the client's behalf: I compare offers from several insurers, and the decision always rests with the client. My advice is free of charge to the client – the brokerage remuneration is paid by the insurer.

MNB registration number: 114063010758 (verifiable in the MNB institution register) · Operating as a partner of Eurorisk Biztosítási Alkusz Kft. · Main site: tukacs.com · Privacy notice